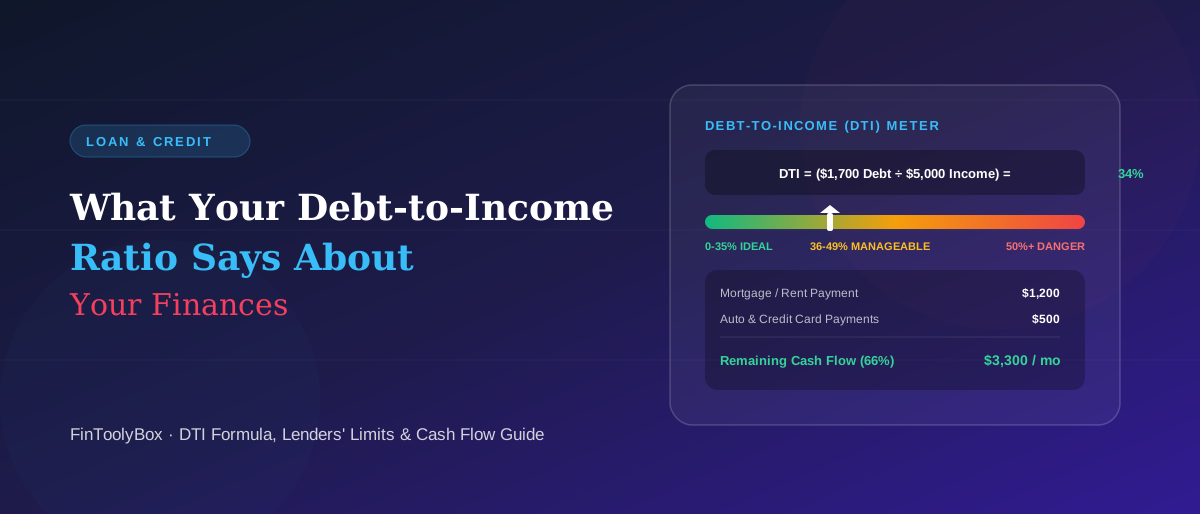
Your Debt-to-Income (DTI) ratio measures what percentage of your gross income goes toward existing debt payments. A lower DTI gives your monthly budget flexibility, protects you during emergencies, and makes qualifying for major loans much easier.
When you apply for a loan, lenders do not only look at your credit score or your salary. They also want to know how much of your income is already being used to pay debts.
One of the simplest ways to measure this is through your debt-to-income ratio, commonly called DTI.
Your DTI can give you a quick picture of how much financial pressure your existing debts are putting on your monthly income. It can also help lenders decide whether taking on another loan would be manageable for you.
What Is Debt-to-Income Ratio?
Debt-to-income ratio compares your monthly debt payments with your gross monthly income.
The basic formula is:
Debt-to-Income (DTI) Formula
DTI = (Total Monthly Debt Payments ÷ Gross Monthly Income) × 100
For example, suppose you earn $5,000 per month before taxes. Your monthly debt payments include:
- $1,200 for a mortgage or rent
- $300 for a car loan
- $200 for credit card minimum payments
Your total monthly debt payments are $1,700.
So your DTI would be: ($1,700 ÷ $5,000) × 100 = 34%.
This means approximately 34% of your gross monthly income is going toward the debts included in the calculation.
Why Does Your DTI Matter?
Your income tells a lender how much money comes in. Your DTI helps show how much of that income is already committed to debt payments.
Two people could earn exactly the same salary but have very different financial situations.
For example, one person earning $5,000 a month might have only $500 in monthly debt payments. Another person earning the same amount might have $2,500 in debt payments.
Their salaries are identical, but their available cash flow is very different.
A higher DTI suggests that a larger portion of your income is already committed to debt, which may make it more difficult to qualify for additional borrowing or comfortably handle another monthly payment (see why loan payments are higher than expected).
What Is a Good DTI?
There is no single DTI percentage that guarantees approval or rejection for every loan. Different lenders and loan programs use different requirements.
| DTI Range | Financial Category | What It Means for Borrowers |
|---|---|---|
| Below 35% | Healthy & Ideal | Plenty of cash flow remains available for savings, investing & emergencies. Easy loan approval. |
| 36% – 49% | Moderate Drag | Debt is manageable, but less room for unexpected expenses or large new loans. |
| 50% or Higher | High Risk | Over half of gross income goes to debt. High financial stress; difficult loan qualification. |
Gross Income vs. Take-Home Pay
One common source of confusion is the income number used in the calculation.
DTI is generally calculated using gross monthly income, meaning your income before taxes and payroll deductions.
However, when managing your personal budget, your take-home pay (net income) is far more useful because that is the actual cash that reaches your bank account.
This distinction matters. A DTI might look reasonable on paper (e.g. 30%), while your take-home income still feels stretched after taxes, insurance, groceries, utilities, transportation, and living costs.
What Counts as Debt?
The debts included in a DTI calculation can vary depending on the lender and loan type. Common examples include:
- Mortgage or rent payments
- Auto loans
- Personal loans
- Student loans
- Credit card minimum payments
- Other recurring debt obligations
Some expenses, such as groceries, utilities, phone bills, and entertainment, generally are not treated as debt payments for the standard DTI calculation. However, they still matter when you're deciding whether you can actually afford another monthly payment.
Why a Low DTI Doesn't Mean You Can Afford Everything
Imagine that you earn $6,000 per month and have only $600 in qualifying debt payments. Your DTI would be 10%, which looks very comfortable.
But what if you also have high rent, expensive childcare, insurance premiums, transportation costs, medical expenses, and other large monthly bills?
Your DTI could still be low while your budget feels tight. That's why you should treat DTI as one financial measurement rather than a complete picture of your financial health.
How to Lower Your Debt-to-Income Ratio
If your DTI is higher than you'd like, there are two basic ways to improve it: reduce your debt payments or increase your income.
1. Pay Down Existing Debt
Reducing credit card balances or personal loans lowers your required monthly payments and directly reduces your DTI (see snowball vs avalanche debt strategy).
2. Avoid Taking on Unnecessary Debt
Before adding another monthly payment, consider whether the purchase is genuinely necessary. A new loan might be affordable today but could make your budget less flexible.
3. Increase Your Income
A higher gross monthly income reduces your DTI if monthly debt payments remain unchanged. A raise, freelance work, or growing business income improves your ratio over time.
4. Review Your Debt Before Applying for a Loan
Calculate your DTI before submitting a loan application. Knowing your numbers ahead of time helps set realistic expectations (see how much house you can afford).
DTI and Your Financial Breathing Room
Even if you're not planning to borrow money, knowing your DTI is useful.
A high debt burden leaves you with little room to deal with emergencies. It also makes it harder to save for goals such as buying a home, investing, or building an emergency fund.
A lower debt burden gives your monthly budget flexibility when income changes or unexpected expenses appear.
The Bottom Line
Your debt-to-income ratio is a simple number, but it tells you a lot about how much of your income is already committed to debt.
A lower DTI gives you more financial breathing room, while a higher DTI can make your budget vulnerable to unexpected expenses and affect your borrowing ability.
Still, don't let one percentage make the decision for you. Look at your complete budget, including everyday living costs, savings, emergency reserves, and future goals.
The goal isn't simply to have a DTI that looks good to a lender. The goal is to build a level of debt that you can comfortably manage in real life.
Sources & References
This DTI guide relies on mortgage underwriting standards and consumer lending disclosures. For official guidance, visit:
- Consumer Financial Protection Bureau (CFPB) What is DTI?
- Fannie Mae Underwriting Guidelines on Debt-to-Income
- FINRA Personal Debt and Credit Education
Frequently asked questions
What is the formula to calculate Debt-to-Income (DTI) ratio?
DTI = (Total Monthly Debt Payments ÷ Gross Monthly Income) × 100. For example, $1,700 monthly debt divided by $5,000 gross income equals a 34% DTI.
What is considered a good DTI ratio for borrowing?
Generally, a DTI of 35% or lower is considered healthy, providing plenty of cash flow cushion. Most mortgage lenders prefer a DTI under 36% to 43%, though some government-backed loans allow higher DTIs.
Does DTI include living expenses like groceries and utilities?
No. Standard DTI calculations only include recurring debt payments (mortgages, car loans, student loans, credit card minimums). However, living expenses must still be factored into your personal budget.
Helpful resources
Internal resources
- Understanding Debt-to-Income Ratio (DTI)
- How Much House Can You Afford?
- Why Loan Payments Are Higher Than Expected
- Snowball vs Avalanche Debt Payoff
- Browse all articles