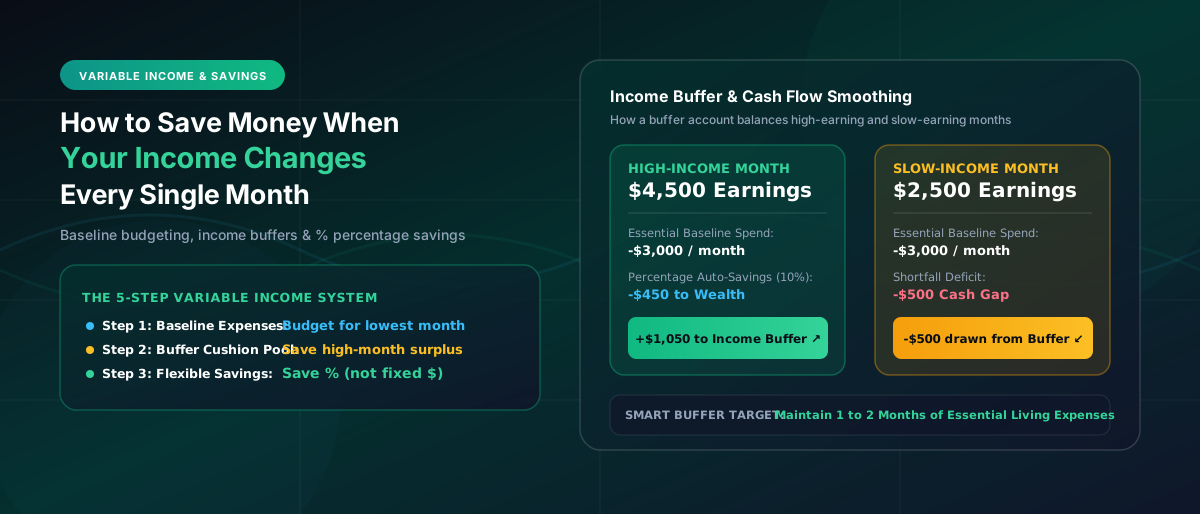
You don't need a fixed salary to build substantial savings. Base your monthly living budget on a conservative baseline income, save a percentage of every incoming payment, and deposit high-month surpluses into an income buffer account to cover lean months smoothly.
Saving money is much easier when you receive the same paycheck every month. You know roughly how much is coming in, you can plan your bills, and you can decide how much to put aside.
But what happens when your income changes from month to month?
If you're self-employed, freelance, working on commission, running a small business, doing contract work, or simply earning irregular income, creating a savings plan can feel difficult. One month might be excellent, while the next barely covers your regular expenses.
The good news is that you don't need a perfectly predictable income to build savings. You simply need a system that can handle both good and bad months.
Build Your Budget Around Your Lowest Normal Income
One of the safest ways to manage irregular income is to create your basic budget around a conservative income amount.
Instead of asking, "How much did I earn last month?", look at your income over several months and identify a realistic lower-end amount you can usually expect.
Use that amount to cover your essential expenses, such as:
- Housing or rent
- Food and groceries
- Utilities
- Transportation
- Insurance
- Debt payments
- Other essential bills
This approach can prevent you from building your lifestyle around an unusually good month.
Income Buffer & Cash Flow Smoothing Example
Suppose your essential baseline expenses are $3,000 / month:
High Month ($4,500) → Pay $3,000 Expenses + $450 Savings + Deposit $1,050 into Income Buffer
Slow Month ($2,500) → Pay $2,500 Earnings + Draw $500 from Income Buffer = $3,000 Covered!
By depositing surplus cash in prosperous months and drawing down during slow months, your monthly living standard remains completely stable.
| Monthly Earnings | Percentage Savings (10%) | Baseline Living Budget | Buffer Pool Allocation | Financial Health Result |
|---|---|---|---|---|
| $2,000 (Slow) | $200 / month | $2,500 / month | -$700 (Draw Buffer) | Protected by Buffer Pool |
| $3,500 (Normal) | $350 / month | $2,500 / month | +$650 (Deposit Buffer) | Buffer Replenished |
| $5,000 (Strong) | $500 / month | $2,500 / month | +$2,000 (Deposit Buffer) | Buffer Full + Extra Investments |
| $7,000 (Peak) | $700 / month | $2,500 / month | +$3,800 (Wealth Acceleration) | Major Goals Funded |
Separate Your Money Into Different Buckets
When your income changes constantly, keeping everything in one account can make your finances difficult to understand.
Consider separating your money into different purposes. For example, you might have one account or category for everyday spending, another for bills, and another for savings.
This doesn't necessarily mean you need multiple bank accounts. Even simple budgeting categories can help you see what your money is supposed to do (learn how to build a monthly budget you can stick to).
The goal is to avoid spending money today that you'll need for a bill next month.
Create an Income Buffer
An income buffer can be especially useful when your earnings are unpredictable.
Instead of spending every dollar during a high-income month, keep some money available to help cover expenses during a slower month.
For example, imagine you earn $4,500 one month but only $2,500 the following month. If your essential expenses are $3,000, the extra money from the first month can help fill the gap.
Over time, you can build a larger buffer that makes your monthly finances feel much more stable.
Don't Set One Rigid Savings Amount
With a fixed salary, you might decide to save $500 every month.
That approach may not work when your income changes significantly.
Instead, consider saving a percentage of your income.
For example, you might decide to save 10% of every payment you receive. If you earn $2,000, that's $200. If you earn $5,000, that's $500.
This allows your savings contributions to rise and fall naturally with your income.
Give Extra Income a Job
When you have an unusually strong month, it can be tempting to spend the extra money immediately.
Instead, decide in advance what you will do with income above your normal budget (read why your salary increase might not feel like a raise).
You could divide it between:
- Emergency savings
- Retirement or long-term investing
- Debt repayment
- Upcoming annual expenses
- Business expenses
- A personal spending allowance
You don't have to put every extra dollar into savings. The important part is having a plan so that a good month doesn't automatically turn into a spending month.