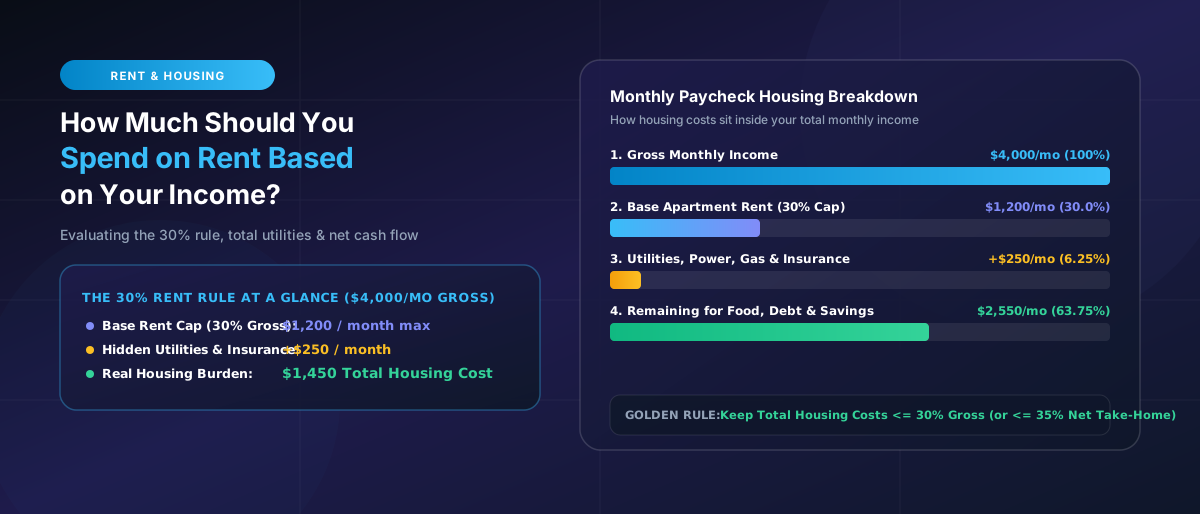
The traditional 30% rent rule suggests capping base rent at 30% of gross monthly income. For a realistic budget, calculate your total housing burden (rent + utilities + parking + insurance) against your net take-home pay, ensuring enough cash remains for savings, food, and debt obligations.
Rent is one of the biggest expenses most people deal with every month. If it takes up too much of your income, you may find yourself struggling to save, pay off debt, or handle unexpected expenses.
So how much should you actually spend on rent?
A common starting point is to keep rent around 30% of your gross monthly income. But that number isn't a perfect rule for everyone. Your income, location, debt, transportation costs, family situation, and financial goals all matter.
What Is the 30% Rent Rule?
The 30% rule suggests that your monthly rent should generally be no more than about 30% of your gross monthly income.
For example, if you earn $4,000 per month before taxes:
$4,000 Gross Income × 30% = $1,200 Monthly Rent Target
It's important to remember that this is a guideline, not a requirement. Someone earning $4,000 a month might comfortably afford $1,400 in rent if they have very few other expenses. Someone else might struggle with $1,200 because of significant debt or other financial responsibilities.
Gross Income vs. Take-Home Pay
One reason rent calculations can be confusing is that there are different ways to measure income (see how taxes affect your take-home pay).
Gross income is what you earn before taxes and other deductions.
Take-home pay is what actually reaches your bank account after taxes and other deductions.
The traditional 30% guideline is generally based on gross income. However, when deciding what you can personally afford, looking at your take-home pay can give you a more realistic picture of your monthly cash flow.
For example, $1,200 of rent may sound reasonable based on a $4,000 gross salary, but you still need to consider how much money you actually have available after taxes.
Rent Affordability Breakdown ($4,000 Gross Salary Example)
Suppose your gross salary is $4,000/month, resulting in $3,000 net take-home pay after taxes:
30% Gross Rent Target: $1,200 Base Rent + $250 Utilities = $1,450 Total Housing
Net Take-Home Remaining: $3,000 Net - $1,450 Housing = $1,550 for Food, Debt & Savings
$1,450 total housing represents 48% of your net $3,000 take-home pay. Ensure your remaining $1,550 covers debt and living comfortably.
| Gross Monthly Income | Est. Net Take-Home Pay | 30% Gross Rent Cap | Est. Utilities & Insurance | Total Housing Burden | Housing % of Net Pay |
|---|---|---|---|---|---|
| $3,000 / month | $2,300 / month | $900 / month | +$200 / month | $1,100 / month | 47.8% |
| $4,500 / month | $3,350 / month | $1,350 / month | +$250 / month | $1,600 / month | 47.7% |
| $6,000 / month | $4,350 / month | $1,800 / month | +$300 / month | $2,100 / month | 48.2% |
| $8,000 / month | $5,650 / month | $2,400 / month | +$350 / month | $2,750 / month | 48.6% |
Don't Forget the Other Costs of Renting
Rent isn't always your complete housing cost.
You may also have to pay for:
- Electricity
- Water and sewer
- High-speed internet
- Gas and heating
- Reserved parking space fees
- Renter's insurance premiums
- Maintenance-related costs not covered by the landlord
Some apartments include utilities in the rent, while others don't. That's why it's better to consider your total housing cost rather than looking at the advertised rent alone.
Example: Two People With the Same Income
Imagine two people each take home $3,500 per month.
Person A pays $1,000 in rent and has very little debt. Person B pays $1,400 in rent and also has a $500 monthly loan payment.
Although both people earn the same amount, their financial situations are very different.
Person B has considerably less money available after fixed expenses. A rent amount that looks affordable on its own may become difficult once all the other bills are included.
This is why rent should never be evaluated in isolation.
Look at Your Entire Monthly Budget
Before signing a lease, list your expected monthly expenses (see how to build a monthly budget you can stick to).
Include:
- Base rent
- Utilities (power, gas, water, internet)
- Food and groceries
- Transportation and transit
- Insurance premiums
- Debt payments
- Subscriptions
- Personal discretionary spending
- Savings reserves (see where to keep emergency savings)
- Other regular expenses
Then see how much money remains after paying everything.
If your proposed rent leaves almost nothing for savings or emergencies, the apartment may be too expensive even if you technically qualify for it.