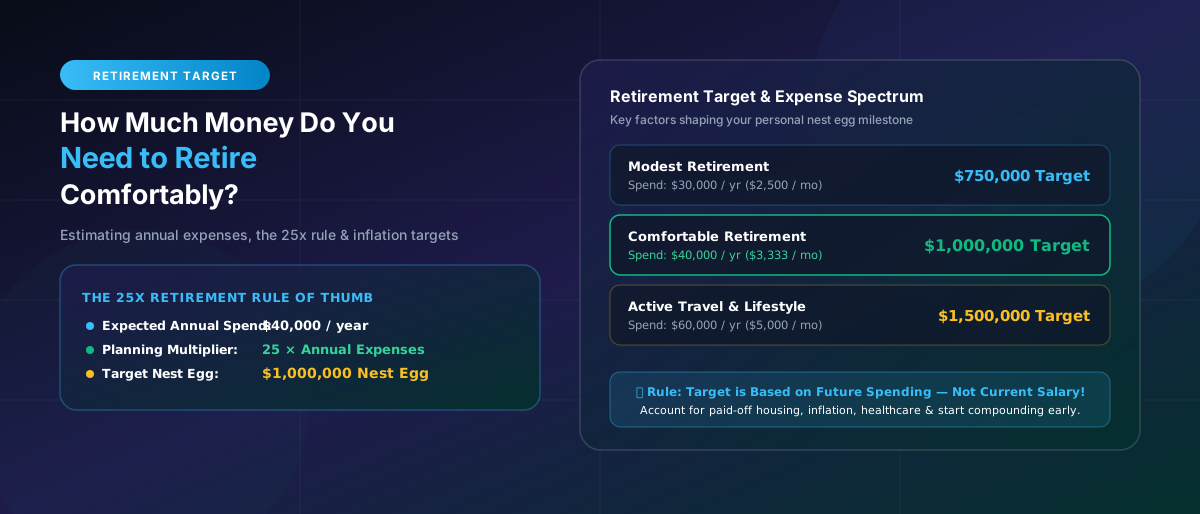
Your retirement target should be based on your expected future spending rather than your current gross salary. Using the 25x rule (25 × annual living costs) gives a realistic target milestone, which can be adjusted based on housing, healthcare, and planned retirement age.
One of the biggest questions people have about retirement is surprisingly simple: How much money do I actually need?
The honest answer is that there is no single number that works for everyone. Someone who wants to travel several times a year will need a different retirement fund from someone who plans to live a quiet life close to home. Your income, lifestyle, location, health, housing costs, and retirement age all matter.
Still, you can get a realistic idea of your retirement target by looking at your expected expenses and building a plan around them.
Start With How Much You Expect to Spend
Your retirement number should be based more on your future spending than your current salary.
For example, imagine you currently earn $5,000 per month but spend around $3,500. You may not need enough retirement income to replace the entire $5,000. Your target may be closer to the amount you actually expect to spend.
Make a list of expenses such as:
- Housing or rent
- Food and groceries
- Utilities
- Transportation
- Healthcare
- Insurance
- Travel and entertainment
- Family support
- Taxes
- Unexpected expenses
Some costs may decrease after you retire, while others could increase. For example, you may no longer have commuting expenses, but you may spend more on healthcare, hobbies, or travel.
A Common Rule of Thumb: 25 Times Your Annual Expenses
One popular starting point is the 25x rule. The basic idea is to estimate your annual retirement expenses and multiply that amount by 25.
The 25x Rule Calculation Example
Suppose you expect to spend $40,000 per year in retirement:
$40,000 annual spend × 25 = $1,000,000 Nest Egg Target
This milestone assumes a ~4% annual portfolio withdrawal rate designed to sustain income over 25 to 30 years.
| Expected Annual Spending | Monthly Budget Equivalent | 25x Nest Egg Target | 4% Safe Annual Withdrawal |
|---|---|---|---|
| $30,000 / year | $2,500 / month | $750,000 | $30,000 / year |
| $40,000 / year | $3,333 / month | $1,000,000 | $40,000 / year |
| $60,000 / year | $5,000 / month | $1,500,000 | $60,000 / year |
| $80,000 / year | $6,666 / month | $2,000,000 | $80,000 / year |
This is only a planning guideline, not a guarantee. Investment returns, inflation, taxes, healthcare costs, how long you live, and the amount you withdraw each year can all affect whether your savings last (see smart savings strategies for long-term wealth).
Your Retirement Age Makes a Difference
Retiring at 60 and retiring at 45 are very different financial goals (see how much to save for retirement by age).
If you retire earlier, your savings may need to support you for a much longer period. You may also have fewer years to contribute to your retirement investments.
On the other hand, working a few additional years can give you more time to save while reducing the number of years your retirement portfolio needs to provide income.
Even a small change in your planned retirement age can significantly affect the amount you need to save.
Don't Forget Inflation
A retirement target that looks large today may not have the same purchasing power decades from now (see how inflation quietly reduces the value of your savings).
For example, if something costs $40,000 per year today, it could cost considerably more in the future because prices generally rise over time.
That's why retirement planning should account for inflation rather than simply assuming that today's expenses will remain unchanged.