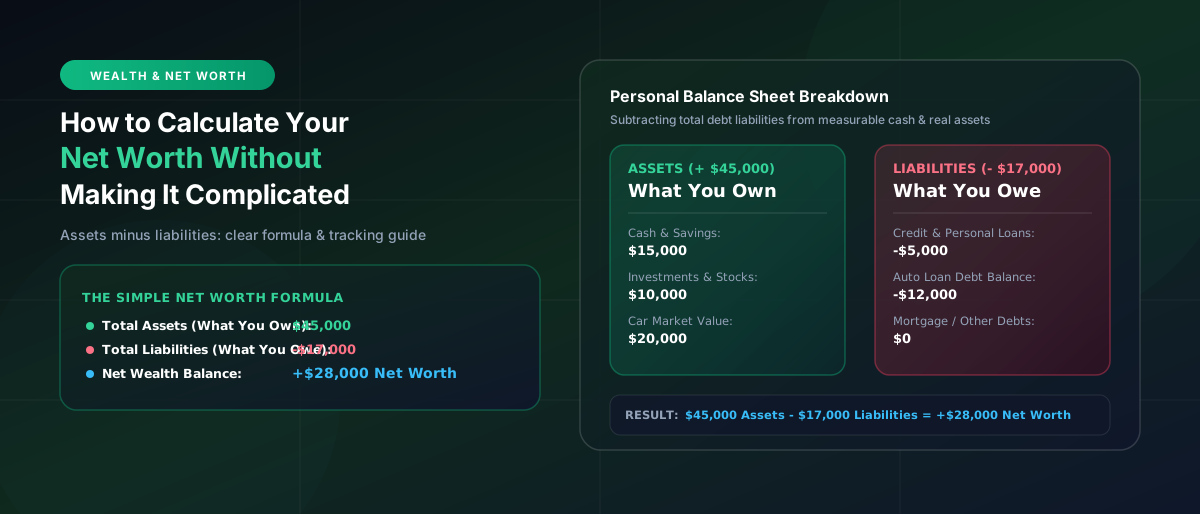
Your net worth is simply what you own (Assets) minus what you owe (Liabilities). You don't need complex spreadsheets. Track major liquid accounts, real estate, and vehicle market values, subtract remaining debt balances, and evaluate your trajectory over time.
When people hear the phrase net worth, they sometimes imagine something reserved for wealthy investors, business owners, or people with complicated financial portfolios.
It really isn't.
Your net worth is simply a snapshot of what you own compared with what you owe. You don't need a huge income, multiple investments, or a complicated spreadsheet to calculate it. In fact, knowing your net worth can be one of the easiest ways to understand where you currently stand financially (see our core guide on understanding net worth).
What Is Net Worth?
Net worth is the value of your assets minus the value of your liabilities.
The basic formula is:
Net Worth = Total Assets − Total Liabilities
Your assets are things that have financial value. Your liabilities are debts or financial obligations you still owe.
Simple Net Worth Calculation Example
Suppose an individual has the following financial snapshot:
- $15,000 in bank savings
- $10,000 in investment stocks
- Car with market value of $20,000
- -$5,000 credit card debt
- -$12,000 remaining auto loan
Total Assets ($45,000) - Total Liabilities ($17,000) = $28,000 Net Worth
That's it. Net worth doesn't need to be complicated.
| Life Stage Profile | Total Measured Assets | Total Debts & Liabilities | Calculated Net Worth | Primary Financial Focus |
|---|---|---|---|---|
| Recent Graduate | $6,000 (Savings & Car) | $28,000 (Student Loan) | -$22,000 | Debt Repayment & Career |
| Early Career Professional | $45,000 (Cash & 401k) | $17,000 (Auto & Credit) | +$28,000 | Emergency Fund & Investing |
| Mid-Career Homeowner | $350,000 (Home & Investments) | $210,000 (Mortgage Balance) | +$140,000 | Mortgage Equity & Retirement |
| Pre-Retiree | $850,000 (Portfolio & Paid House) | $0 (Zero Debt) | +$850,000 | Capital Preservation |
Step 1: List Your Assets
Start by making a list of everything you own that has meaningful financial value.
Common assets can include:
- Cash in checking and savings accounts (see storing emergency cash safely)
- Emergency savings reserves
- Stocks, bonds, mutual funds, and brokerage accounts
- Retirement accounts (401(k), IRA, superannuation)
- Real estate market value
- Vehicles (resale market value)
- Business equity and ownership interests
- Other high-value physical property
You don't necessarily need to include every small possession you own. Your furniture, clothes, and household items may technically have resale value, but estimating them can make the calculation unnecessarily complicated.
Focus on assets that have significant and reasonably measurable value.
Step 2: Estimate What Your Assets Are Worth
Once you've listed your assets, assign a realistic current value to each one.
Your bank balance is easy. If you have $8,000 in a savings account, you can generally count $8,000.
Investments are also relatively straightforward. Use their current market value rather than what you originally paid for them.
Vehicles and property are slightly different. Their current value may not be the same as what you paid.
If you paid $30,000 for a car several years ago, for example, it may be worth considerably less today.
The goal isn't to make your assets look as valuable as possible. You're trying to create a realistic picture of your financial position.
Step 3: List Your Liabilities
Now make a separate list of everything you owe.
Depending on your situation, this could include:
- Credit card balances
- Personal loans
- Auto loans
- Student loans
- Mortgage principal balance remaining
- Business debt obligations
- Other outstanding liabilities
Use the amount you currently owe, not the original amount of the loan.
For example, if you originally borrowed $20,000 for a car and have already paid $8,000 toward the principal, your remaining liability might be around $12,000, depending on the loan.
Step 4: Add Everything Up
Once you have your assets and liabilities, add each category separately.
For example:
Total assets: $100,000
Total liabilities: $65,000
Your net worth would be:
$100,000 − $65,000 = $35,000
If your liabilities are greater than your assets, your net worth can be negative.
That isn't necessarily a sign that you're failing financially. Someone who recently bought a home, started a business, or graduated with student loans may have substantial debts while still building their financial foundation.