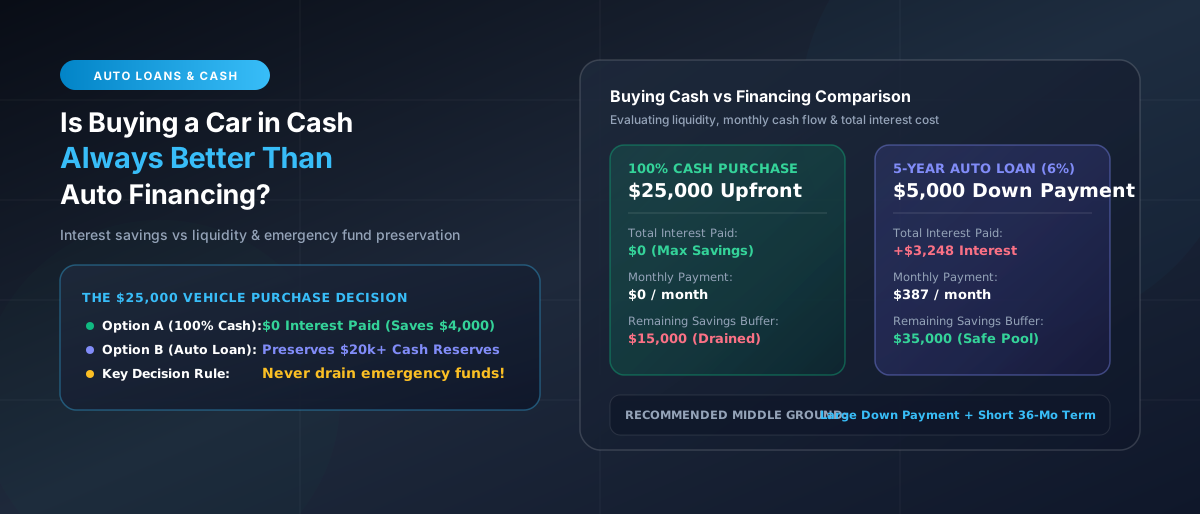
Paying cash for a vehicle completely eliminates interest charges and monthly loan payments. However, if paying 100% cash drains your emergency savings, financing part of the vehicle at a competitive interest rate protects your liquid financial cushion against unexpected life events.
Buying a car is one of those financial decisions where people often hear the same advice: if you can afford to pay cash, you should. It sounds simple. Avoid a car loan, avoid interest, and own the vehicle outright from day one.
But is paying cash always the smartest choice?
Not necessarily. Financing a car can sometimes make sense, especially when the interest rate is low and keeping your cash available serves a better purpose. The right decision depends on your savings, income, credit, loan terms, and what else you could do with the money.
What Does Buying a Car in Cash Really Mean?
Buying a car in cash means you pay the full purchase price without taking out an auto loan. If the car costs $25,000 and you pay $25,000 upfront, you have no monthly car payment and no loan interest.
That can be financially attractive because the cost of borrowing disappears. Once the purchase is complete, your main vehicle expenses are things such as insurance, fuel, maintenance, registration, and repairs.
The downside is that a large amount of money leaves your bank account at once.
The Biggest Advantage of Paying Cash
The most obvious benefit is avoiding interest.
Suppose you finance a $25,000 car and eventually pay $29,000 over the life of the loan. The extra $4,000 represents money that could have stayed in your pocket if you had paid cash.
There is also something valuable about not having another monthly bill. Without a car payment, more of your income can go toward savings, investing, housing, debt repayment, or other goals.
Paying cash can also make your monthly budget more predictable. You still have vehicle expenses, but you do not have a loan payment hanging over you for several years.
Car Cash vs. Financing Tradeoff Example ($25,000 Car)
Suppose you have $40,000 total savings and want to buy a $25,000 vehicle:
100% Cash: $0 Loan Interest Paid | Remaining Emergency Savings: $15,000
5-Yr Loan (6% APR, $5k Down): $3,248 Interest Paid | Remaining Emergency Savings: $35,000
If $15,000 is too thin for your household emergency reserve, preserving $35,000 in cash via financing can be a safer financial decision.
| Purchase Strategy | Down Payment | Monthly Payment | Est. Interest Paid | Post-Purchase Cash Cushion |
|---|---|---|---|---|
| 100% Cash Purchase | $25,000 upfront | $0 / month | $0 (Max Savings) | $15,000 remaining |
| 50% Down (36-Mo Loan @ 5%) | $12,500 upfront | $374 / month | +$975 interest | $27,500 remaining |
| 20% Down (60-Mo Loan @ 6.5%) | $5,000 upfront | $391 / month | +$3,485 interest | $35,000 remaining |
| Manufacturer 0.9% Promo Loan | $2,500 upfront | $383 / month | +$515 interest | $37,500 remaining |
But Cash Isn't Completely Free
This is where the decision becomes more interesting.
Imagine you have $40,000 saved and want to buy a $25,000 car. Paying cash would leave you with only $15,000.
If that $40,000 represents most of your savings, using $25,000 for a car could leave you financially vulnerable. A job loss, medical bill, major home repair, or other emergency could suddenly become much harder to handle (see where to store your emergency fund savings).
In that situation, financing part of the car might be reasonable if it allows you to keep a healthy emergency fund.
When Financing Can Make Sense
Financing isn't automatically a bad financial decision. The interest rate is one of the biggest factors to consider.
If a lender offers you a relatively low rate, you may decide that keeping your cash available is worth the cost of the loan (learn how to tell if a loan offer is actually a good deal).
For example, instead of spending $25,000 from your savings, you might make a substantial down payment and finance the remaining amount. This gives you a smaller loan while preserving some cash.
Financing can also make sense if your cash has an important job already. You might need it for an emergency fund, a business, a home purchase, education, or another financial priority.
The key is not simply asking, “Can I afford the monthly payment?” You should ask, “What is the total cost of this loan, and what am I giving up by paying cash?”
Don't Focus Only on the Monthly Payment
A common mistake when shopping for a car is focusing heavily on the monthly payment (see how much interest you pay on a 5-year loan).
A $400 monthly payment might sound manageable. But if the loan lasts six or seven years, you could end up paying significantly more for the vehicle.
Always look at:
- The vehicle's total purchase price
- Your down payment amount
- The principal amount financed
- The interest rate and APR
- The total loan duration (months)
- Total cumulative interest paid
- Any origination or loan documentation fees
- The total overall amount repaid
A longer loan can reduce the monthly payment while increasing the total amount you pay.